The direct deposit hits on a Friday.
Not a campus refund. Not birthday money from your aunt. An actual paycheck from an actual job — the first one that feels like the start of adult life.
You open the banking app in the parking lot (or on the bus, or on your parents’ Wi-Fi if you’re home for a minute). The number isn’t huge. But it’s yours.
And suddenly every store, every ad, every “treat yourself” voice in your head has something to say.
Before you spend a dollar of it, there’s a mindset principle worth locking in:
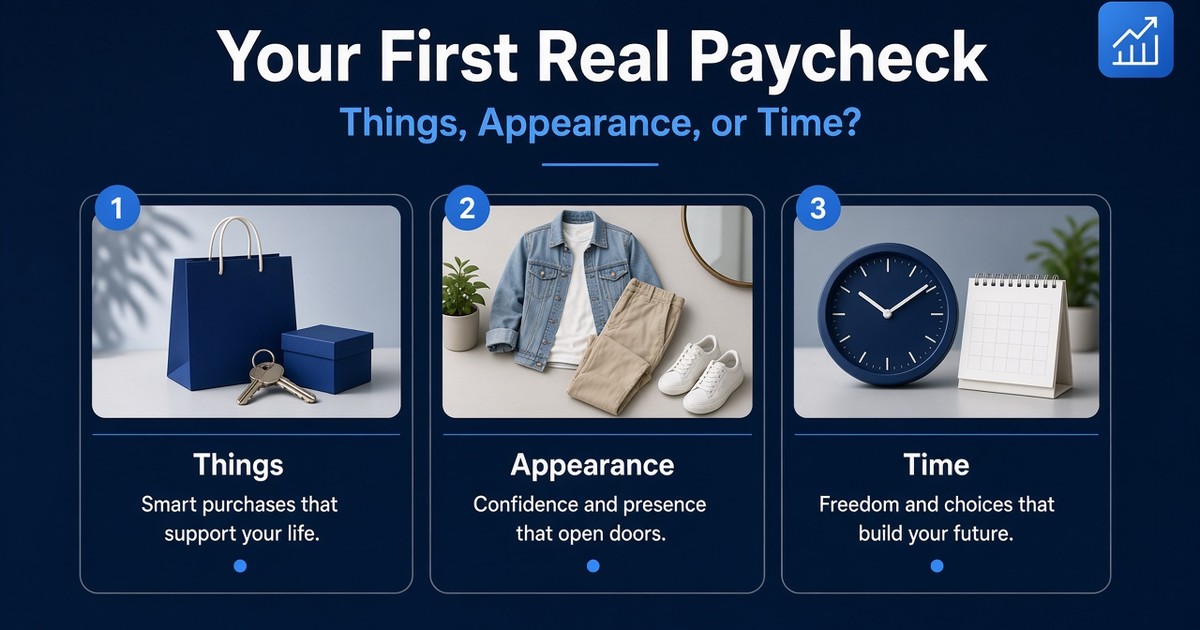
Poor buy things.
Middle class buy appearance.
Rich buy time.
It’s not an insult. It’s a map.
Not about your parents’ tax bracket. Not about shaming a first paycheck. It’s about what money is for — and which story your next purchase funds.
The week the money felt like permission (buying things)
By Sunday you’ve already done the math in your head twelve different ways.
There’s the laptop that’s “basically for work.”
There’s the sneakers you’ve wanted since junior year.
There’s dinner out because cooking feels like dorm life and you’re done with that chapter.
None of that makes you reckless. It makes you human.
When money has been scarce for a long time — student budgets, shared groceries, watching every swipe — buying a thing can feel like progress. Proof the grind worked. A little evidence that life is leveling up.
That’s the first line of the principle in real life: poor buy things — not because people with less are foolish, but because when cash is tight, anything you can finally purchase feels like forward motion.
So you buy the thing.
It feels great for about 72 hours.
Then the high fades, the box is empty, and the next paycheck isn’t here yet. The scoreboard resets. You’re back to waiting for another hit of “I made it.”
That’s the quiet trap of spending in scarcity mode:
money comes in → money becomes stuff → money is gone → pressure returns.
The LinkedIn-looking version of the same mistake (buying appearance)
A few months in, the temptation shifts.
It’s not just stuff anymore. It’s the look of having it together.
You notice what people from your class are posting.
New apartment aesthetic.
A nicer car than the one that got you through finals week.
Weekend trips that photograph like a highlight reel.
Nobody says “I’m buying appearance.” They say “I’ve earned this.”
And maybe you have earned rest. Celebration. Joy.
But there’s a difference between celebrating and performing.
That’s the second line of the principle: middle class buy appearance — spending that signals success to other people before the foundation is built. It’s the biggest mistake of early career money, because it feels like winning while it quietly shrinks your options.
Appearance spending is when the purchase is mostly for the audience — coworkers, classmates, the version of you that wants to look successful before the foundation is built.
The upgraded lease before any cash cushion.
The wardrobe refresh timed to your first office photos.
The dinner tab you cover because it feels like who you’re supposed to be now.
It doesn’t feel irresponsible in the moment. It feels like belonging.
The bill shows up later as less flexibility: thinner savings, sticky debt, fewer options when a tire blows or a roommate bails or the job isn’t forever.
Looking rich and building wealth are not the same project.
One is a feed.
The other is a system.
The night someone buys time instead
Somewhere in that first year, you meet a different kind of choice.
Maybe it’s a coworker who looks calm on a random Tuesday.
Maybe it’s an older cousin who isn’t flashy but somehow never panics about money.
Maybe it’s just you, staring at your account after another “I deserve this” weekend, asking a better question:
What if this paycheck could buy me time?
That’s the third line of the principle: rich buy time — not mystical “rich people energy,” but practical spending on software, services, buffers, and assets so money starts working with you.
Buying time looks ordinary up close:
- software that does a boring task so you get an evening back
- a simple automatic transfer you don’t have to “remember” every two weeks
- paying for help or tools that protect focus when you’re building skills at your first job
- putting money into a buffer so one surprise doesn’t become a crisis
- starting investments so your future self isn’t starting from zero at 35
Buying time is buying options.
It’s the difference between money that only disappears through you… and money that starts working with you.
Things can still be fun.
Looking put-together can still matter.
But if your first real income only funds consumption and image, you’re rehearsing a life that always needs the next deposit to feel okay.
If some of it buys time — buffer, freedom from debt, ownership of assets — you’re rehearsing a different future.
Mindset check before you swipe
Keep the principle where you can see it:
| Mindset | Money’s job | What gets purchased |
|---|---|---|
| Scarcity | Prove progress right now | Things |
| Status | Signal success to others | Appearance |
| Leverage | Create options and freedom | Time |
Poor / middle class / rich here aren’t permanent labels. They’re default settings. You can earn a solid salary and still buy appearance. You can start small and still practice buying time.
Income matters. Perspective decides what income becomes.
So how should a new grad spend first real money?
Forget perfect. Aim for sequence.
Before the sneakers-and-status era eats the whole story, give your paycheck a job in this order — the practical way to “buy time” with a first job:
1. Build 3–6 months of savings (your emergency fund)
Park cash somewhere boring and reachable for real emergencies — job gaps, medical surprises, car repairs — not for sales and vibes.
This is the first real “buy time” move most people skip. A cushion buys calm. Calm buys better decisions.
2. Knock out any debt
Student loans, credit cards, the “I’ll handle it later” balances that grew during school. High-interest debt especially steals future options.
Every payment that shrinks what you owe buys back tomorrow’s paycheck.
3. Start investing
Once the buffer is forming and debt is under attack, begin investing consistently — even small amounts — so time can do some of the heavy lifting.
You don’t need a complicated strategy to start. You need a habit that outlasts your first job title.
That’s the spine in real life:
- Things satisfy a moment
- Appearance performs a moment
- Time (savings, less debt, investments) compounds into freedom
Your first paycheck isn’t just money.
It’s your first chance to choose which story you’re funding.
Poor buy things. Middle class buy appearance. Rich buy time.
Now that the money is real — which one are you practicing?
Want more practical guides for this stage of life? Explore more on Help Your Finances, or join the newsletter for clear, no-drama personal finance while you build your foundation.
This article is for educational and informational purposes only. It is not financial, investment, tax, or legal advice. Consider your own situation and, if needed, consult a qualified professional.