Here’s the question I get in different words all the time:
If I had $500,000, how would I set it up for monthly living money — without wrecking the nest egg?
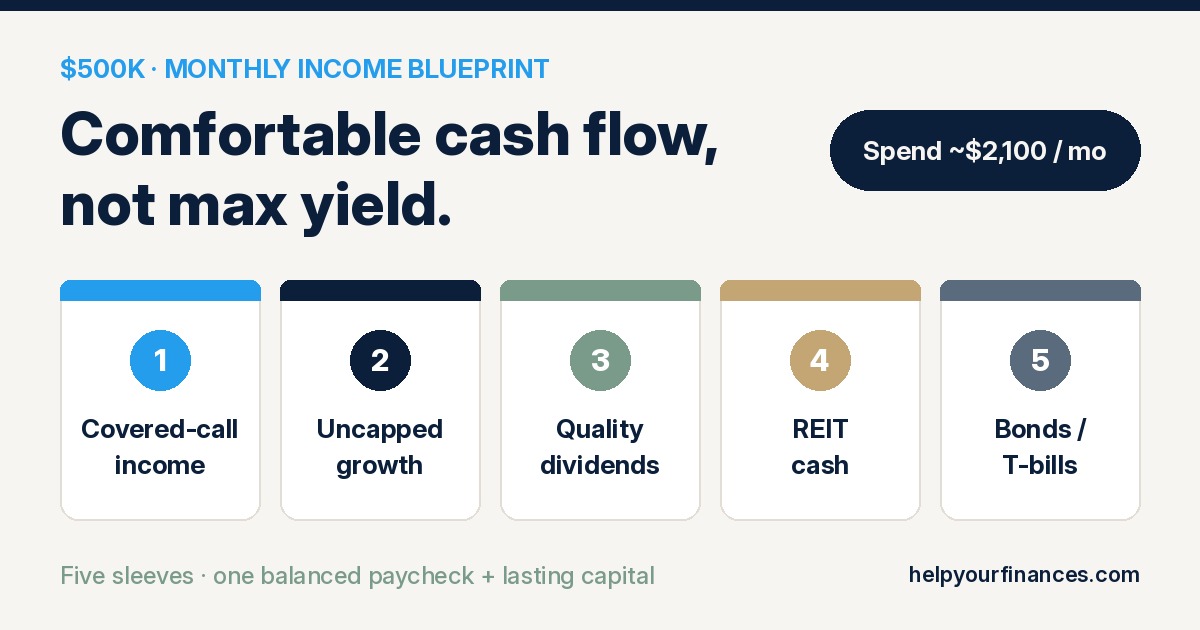
Short answer: aim for comfortable cash flow, not the loudest yield. On $500k, a ~5% spend (~$2,100/month) is the sweet spot I’d design around. The blueprint below blends to about ~5.7% / ~$2,380/month in distributions (late October 2026 yield snapshot) so you can live near $2,100, reinvest the surplus, and keep dry powder for ugly years.
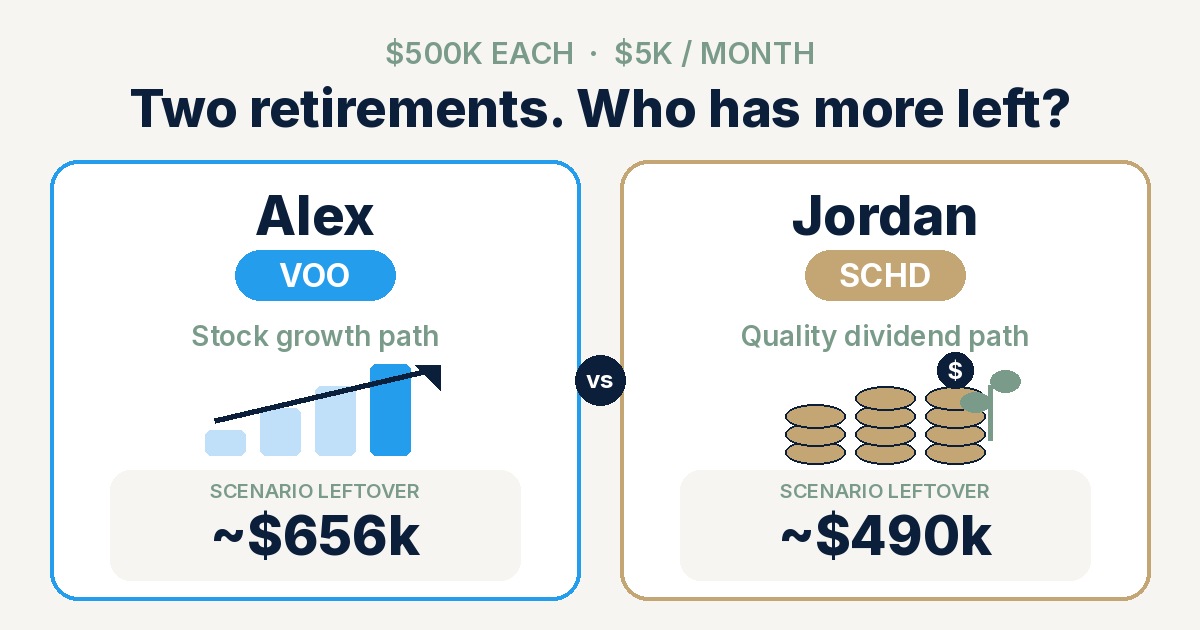
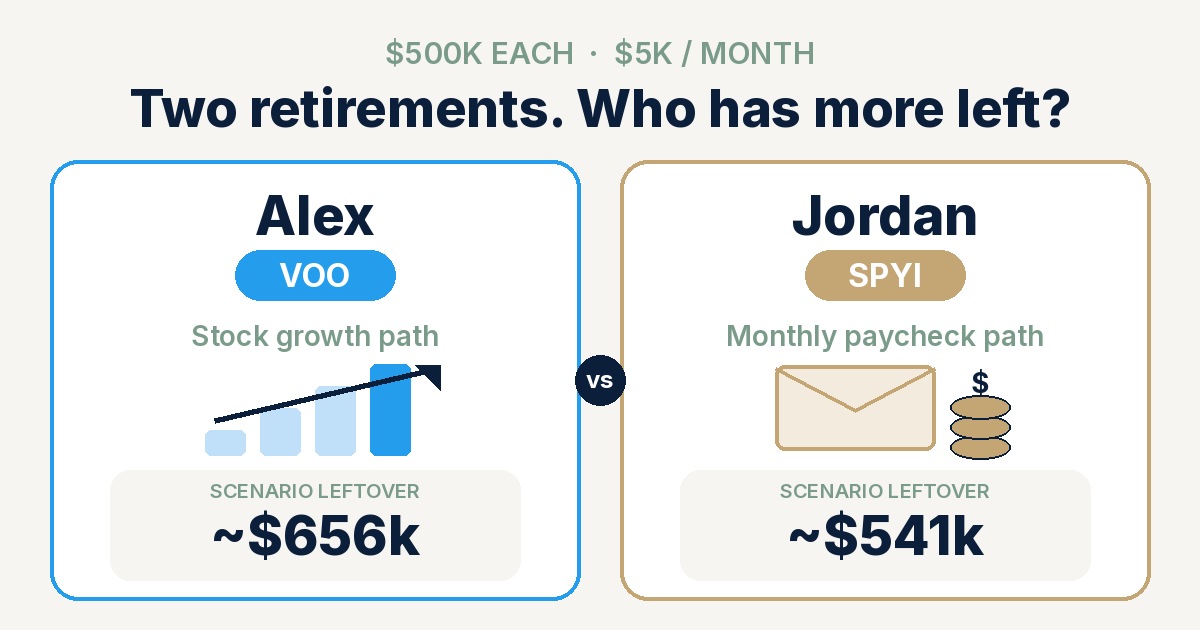
What this is not: a promise that $500k safely throws off $5,000/month forever. That’s ~12% — drawdown math, not perpetuity. Our living-off sims already showed what happens when the monthly need outruns what the portfolio quietly produces (SPYI vs VOO, SCHD vs VOO).
This is an educational blueprint — a suggestion frame, not personalized advice.
The tradeoff in one sentence
Max headline yield and capital that lasts pull in opposite directions.
Chase 10–12%+ distributions and you often buy NAV grind, return-of-capital theater, or funds that sell away the rebound you need after a crash. That’s the high-yield trap in portfolio form.
Build only for growth and you may sell shares every month for rent — fine in a bull market, stressful when prices fall.
The middle path: sensible covered-call income (JEPI / JEPQ style) + uncapped growth sleeves + quality dividends + REIT cash + bond/T-bill ballast so you’re not a forced seller in a recession.
The “Bulletproof Living” allocation ($500k)
Yields below are a late October 2026 window snapshot (JEPI’s ~8.0% uses a ~8.04% 12-month rolling figure as of Sep 30). They move. Re-check before you act.
| Ticker | Alloc | $ on $500k | Yield used | Approx. annual | Role |
|---|---|---|---|---|---|
| JEPI | 25% | $125,000 | ~8.0% | ~$10,000 | S&P covered-call income workhorse — lower beta, monthly |
| JEPQ | 15% | $75,000 | ~11.6% | ~$8,700 | Nasdaq covered-call income — sized smaller (bigger drawdowns) |
| VOO | 10% | $50,000 | ~1.1% | ~$550 | Uncapped S&P recovery / growth |
| QQQM | 5% | $25,000 | ~0.5% | ~$125 | Uncapped Nasdaq growth sleeve |
| SCHD | 12% | $60,000 | ~3.0% | ~$1,800 | Quality dividends — recession-resilient equity income |
| O | 10% | $50,000 | ~5.7% | ~$2,850 | Monthly REIT cash flow |
| VNQ | 5% | $25,000 | ~3.5% | ~$875 | Broad REIT diversifier vs single-name O |
| BND | 10% | $50,000 | ~4.2% | ~$2,100 | Bond ballast / flight-to-quality |
| SGOV | 8% | $40,000 | ~3.8% | ~$1,520 | T-bill living float / dry powder |
| Total | 100% | $500,000 | ~5.7% blend | ~$28,520 (~$2,380/mo) |
Spend rule of thumb: take ~$2,000–$2,200/month for living (~4–5%). I’d pick ~$2,100/month (~5%), and reinvest whatever distributions come in above that. The ~$2,380 blend gives you a small cushion — not a mandate to spend every dollar the portfolio throws off.
Why each sleeve is there
JEPI (25%) — the income workhorse
Active large-cap equity plus out-of-the-money S&P call overlays. Monthly distributions. The point isn’t “highest yield on earth” — it’s usable income without leaning as hard into the ATM buy-write / heavy return-of-capital patterns you see in some high-yield covered-call cousins. This is the core “paycheck from stocks” sleeve.
JEPQ (15%) — Nasdaq income, deliberately smaller
Same idea on Nasdaq: income expression of growth tech, higher premiums when volatility is elevated. Keep it smaller than JEPI because Nasdaq drawdowns hurt more. You’re buying cash flow, not a full-size uncapped tech bet.
VOO (10%) + QQQM (5%) — uncapped rebound
Covered-call funds sell some upside for premium. When markets recover hard off a low, plain VOO and QQQM are how this portfolio participates. Our living-off stories already showed how much that uncapped path can matter for leftover wealth — even when income funds “feel” better month to month.
SCHD (12%) — real equity dividends
Quality dividend companies, not distribution engineering. Yield is modest (~3% here), but the cash is equity dividends — and this sleeve tends to hold up better psychologically (and often fundamentally) when pure growth stalls. It’s a sleeve, not a $5k/month machine on $500k alone — which is exactly what the SCHD vs VOO spend-down made concrete.
O (10%) + VNQ (5%) — monthly REIT cash, diversified
Realty Income (O) is popular for a reason: monthly checks. Cap the size — REITs are rate-sensitive. VNQ broadens that real-estate income so you’re not married to one landlord ticker.
BND (10%) — recession ballast
When equities panic, high-quality bonds are the “flight to quality” sleeve. Duration isn’t free (rates can sting), but a portfolio that is only equity + covered calls is not recession-aware.
SGOV (8%) — living float so you’re not a forced seller
About $40k is roughly 6–8 months of a ~$2,100 spend. In a crash, you tap T-bills instead of dumping JEPI/JEPQ/VOO at the bottom. That’s the “bulletproof” part people skip when they max every dollar into yield.
What to skip (or keep tiny)
QYLD-style ATM buy-writes that grind NAV while advertising fat yields — the classic covered-call income trap when total return is what actually funds your life.
Weekly ultra-high covered-call products built for yield screenshots, not decade-long living.
BLOX-style / exotic yield traps that confuse a distribution rate with wealth. If the pitch is mostly the percentage, walk away — high-yield trap.
SPYI as a large core? Optional small satellite only if you accept that distributions often include return of capital and that capped upside showed up clearly in the SPYI vs VOO living-off story. For the main income engines here, I’m favoring JEPI / JEPQ-style design over maxing SPYI.
$5,000/month from $500k as “safe income.” That’s ~12%. Possible for a while if you sell shares or chase yield — not a perpetuity plan.
How I’d actually live on it
- Set the paycheck target at ~$2,100/month (or your real budget if lower).
- Let distributions land (JEPI/JEPQ/O/SCHD/etc. hit on different calendars — that’s fine).
- Spend the target; reinvest the surplus into the underweight sleeve or back into VOO/QQQM/SCHD.
- Keep SGOV topped up after big equity months so the crash buffer doesn’t silently disappear.
- Rebalance once or twice a year, not every headline.
You’re optimizing for sleep-at-night income, not winning a yield contest.
Quick FAQ
Can $500k safely pay $5,000 a month forever?
Not as “safe income.” $5k × 12 = $60k = 12% of $500k. That’s a spend-down rate unless returns (and luck) are extraordinary. Design for ~4–5% if perpetuity matters; treat $5k as a deliberate drawdown plan.
Why not 100% JEPI or JEPQ?
Concentration risk, capped upside, and no dry powder. Income workhorses work better beside growth, quality dividends, and cash/bonds — not instead of them.
Why include VOO and QQQM if the goal is income?
Because income funds sell upside. After a bear market, uncapped sleeves are how the pile heals. Without them, you’re funding lifestyle while permanently capping recovery.
Is this the same as the Keep Calm portfolio?
Related spirit (VOO / QQQM / SCHD as calm equity building blocks), different job. Keep Calm is more “build and hold.” This blueprint is explicitly monthly living + ballast on a fixed $500k.
What if yields drop next year?
They will, eventually. That’s why the spend target (~5%) sits under today’s ~5.7% blend, and why SGOV exists. Yield is an input, not a contract.
The takeaway
On $500k, I’d rather collect about ~$2,380/month of blended distributions and spend ~$2,100, than stretch for a $5k screenshot that eats the principal.
JEPI + JEPQ for sensible covered-call income.
VOO + QQQM for uncapped growth.
SCHD for quality dividends.
O + VNQ for REIT cash (sized with respect).
BND + SGOV so a recession doesn’t force you to sell the farm.
Comfortable living and perpetuity can share a portfolio — if you stop asking yield to do a job it can’t.
Disclaimer
Educational suggestion only — not financial, tax, or investment advice. Yields and dollar estimates reflect a late October 2026 snapshot and will change. Allocations are illustrative. Past distributions do not guarantee future income. Covered-call ETF distributions can vary and may include return of capital. Consider your own spending need, tax situation, time horizon, and risk tolerance — and a qualified professional if you need advice.